

The earlier you purchase our Financial-Accounting-Reporting exam prep the faster you pass exam Financial-Accounting-Reporting. Could you believe that? I can tell you that all candidates pass exam with our exam prep. Don't waste your time on one more time Financial-Accounting-Reporting exam. Most of our customers pass exam at first shot. What are you hesitating for? Time is money. Opportunity knocks but once. We are engaged on Financial-Accounting-Reporting exam prep study many years and we can guarantee you pass exam for sure. Trust me, professionals be professionals. You need to do more things what you enjoy.
Our education experts are studying Admission Test Financial-Accounting-Reporting exam prep many years. We edit all questions and answers based on real exam forecast and past real exam characters. In most situations our exam prep can include more than 80% questions of the real test. Also we make out the software version of Financial-Accounting-Reporting exam prep so that you can simulate the real Financial-Accounting-Reporting exam scene and practice more times. Our on-line APP version is popular by many young people. Studying can be more interesting and convenient anywhere. We helped more than 100000+ candidates pass exam in past. If you spend all your attention on our exam prep one or two days before the real test and master all questions and answers I believe you will pass Financial-Accounting-Reporting exam as what we say.

Instant Download: Upon successful payment, Our systems will automatically send the product you have purchased to your mailbox by email. (If not received within 12 hours, please contact us. Note: don't forget to check your spam.)
Not only our Financial-Accounting-Reporting exam prep is accurate and valid to help you pass exam but also we have good customer service. We aim to satisfy every customer at our best.
1. We guarantee all candidates can pass exam. If you fail the exam please provide us your failure mark Admission Test certification we will refund you all the exam prep Financial-Accounting-Reporting cost. No Help, Full Refund! Or you can choose to change other exam subject. (Certified Public Accountant (Financial Accounting & Reporting))
2. Our working time is 7*24 (including the official holidays). Whenever you contact with us we will reply you in three hours. It is our pleasure to serve for you. We are happy to solve with you no matter you have any question or doubt about Financial-Accounting-Reporting exam prep materials or other relating information.
3. For each customer we provide one-year service warranty. We will send you the latest Financial-Accounting-Reporting exam prep within this year once it updates. You can ask us all questions about Admission Test certification examinations we try our best to reply you.
4. Our Admission Test department experts will check the exam prep update version. Once it updates we will refresh the website with the latest Financial-Accounting-Reporting version and we will send the latest version to all our customers ASAP. We make sure all Financial-Accounting-Reporting exam prep for sale are accurate and valid latest versions.
5. We provide the free demo download of Financial-Accounting-Reporting exam prep for your reference before purchasing. After you pay we will send you the download link and password for your downloading in a minute. If you find you purchase the wrong exam code we will exchange for you one time.
6. We have discount for old customers. If you stand for your company which wants to build long-term relationship with us we can talk about the discount details. Our official holiday coupon will be sent to old customers first.
If you want to know more you can contact with us in any time. Trust me, we are the best provider of Financial-Accounting-Reporting exam prep with high passing rate to help you pass CPA Certification Financial-Accounting-Reporting exam 100% not only our exam prep is accurate & valid but also our customer service is satisfying.
Admission Test Financial-Accounting-Reporting Exam Syllabus Topics:
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Select Transactions | 25% - 35% | - Accounting and Reporting Transactions
|
| Topic 2: Financial Reporting | 30% - 40% | - General Purpose Financial Reporting
|
| Topic 3: Select Balance Sheet Accounts | 30% - 40% | - Assets, Liabilities and Equity
|
Admission Test Certified Public Accountant (Financial Accounting & Reporting) Sample Questions:
Taft Corp. discloses supplemental industry segment information. The following information is available for 1992: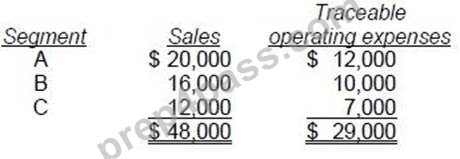
Additional 1992 expenses, not included above, are as follows:
Indirect operating expenses $7,200
General corporate expenses 4,800
Segment C's 1992 operating profit was:
- A. $3,200
- B. $5,000
- C. $2,000
- D. $2,600
Correct Answer: B 🗳️
The summary of significant accounting policies should disclose the:
- A. Concentration of credit risk of all financial instruments by geographical region.
- B. Terms for convertible debt to be exchanged for common stock.
- C. Maturity dates of noncurrent debts.
- D. Criteria for determining which investments are treated as cash equivalents.
Correct Answer: D 🗳️
Opto Co. is a publicly-traded, consolidated enterprise reporting segment information. Which of the following items is a required enterprise-wide disclosure regarding external customers?
- A. Information on major customers is not required in segment reporting.
- B. The identity of any external customer providing 10% or more of a particular operating segment's revenue.
- C. The identity of any external customer considered to be "major" by management.
- D. The fact that transactions with a particular external customer constitute more than 10% of the total enterprise revenues.
Correct Answer: D 🗳️
Hyde Corp. has three manufacturing divisions, each of which has been determined to be a reportable segment. In 1989, Clay division had sales of $3,000,000, which was 25% of Hyde's total sales, and had operating costs of $1,900,000, as reported to the CFO. In 1989, Hyde incurred operating costs of $500,000 that were not directly traceable to any of the divisions. In addition, Hyde incurred corporate interest expense of $300,000 in 1989. In reporting segment information, what amount should be shown as Clay's operating profit for 1989?
- A. $975,000
- B. $875,000
- C. $900,000
- D. $1,100,000
Correct Answer: D 🗳️
Thorpe Co.'s income statement for the year ended December 31, 1990, reported net income of $74,100. The auditor raised questions about the following amounts that had been included in net income: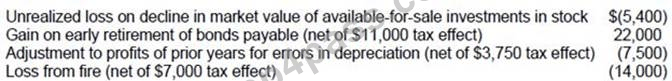
The loss from the fire was an infrequent but not unusual occurrence in Thorpe's line of business.
Thorpe's December 31, 1990, income statement should report net income of:
- A. $81,600
- B. $87,000
- C. $65,000
- D. $66,100
Correct Answer: B 🗳️


 Priscilla

 Jocelyn

 Charles

 Joa
 Virginia
 Lennon
 Amy
 Carol
 Marian
 Faithe
 Booth
 Angelo
 Aurora
 Astrid
 Lionel


